$AMBP, $4.68. According to PennyGems App stock analysis ardagh Metal Packaging offers two reasons to look beyond a low share price: a business that can earn more from its existing operations and a potential ownership transaction that could change how investors assess it. Those are separate propositions. Either could support an investment case; neither makes a takeover premium or a rising share price inevitable.
The most defensible bullish argument is that repeatable operating improvement could increase the value attributable to ordinary shareholders. A sale process could be an additional catalyst, but buying solely in anticipation of a deal would leave the investment dependent on terms that have not been announced.
Earnings improve, but volumes tell a different story
In its July 23 second-quarter release, Ardagh reported adjusted EBITDA of US$240 million, up 14%, while global beverage-can shipments fell 1%. Management raised its full-year adjusted EBITDA outlook to US$775–790 million. These are adjusted measures and management forecasts, not guarantees of future earnings. [1]
For an investor, the useful question is whether profitability can hold up when temporary advantages fade. Selling more products and earning more on each product are different routes to growth. An earnings increase without corresponding shipment growth deserves a closer examination of pricing, costs and the timing of recoveries.
The bullish interpretation is that the company can improve its economics before a broader volume recovery arrives. The skeptical interpretation is that the reported improvement may flatter the underlying run rate. Future quarters should help distinguish those possibilities; extrapolating the strongest quarter would not.
What the supplied AMBP chart actually shows
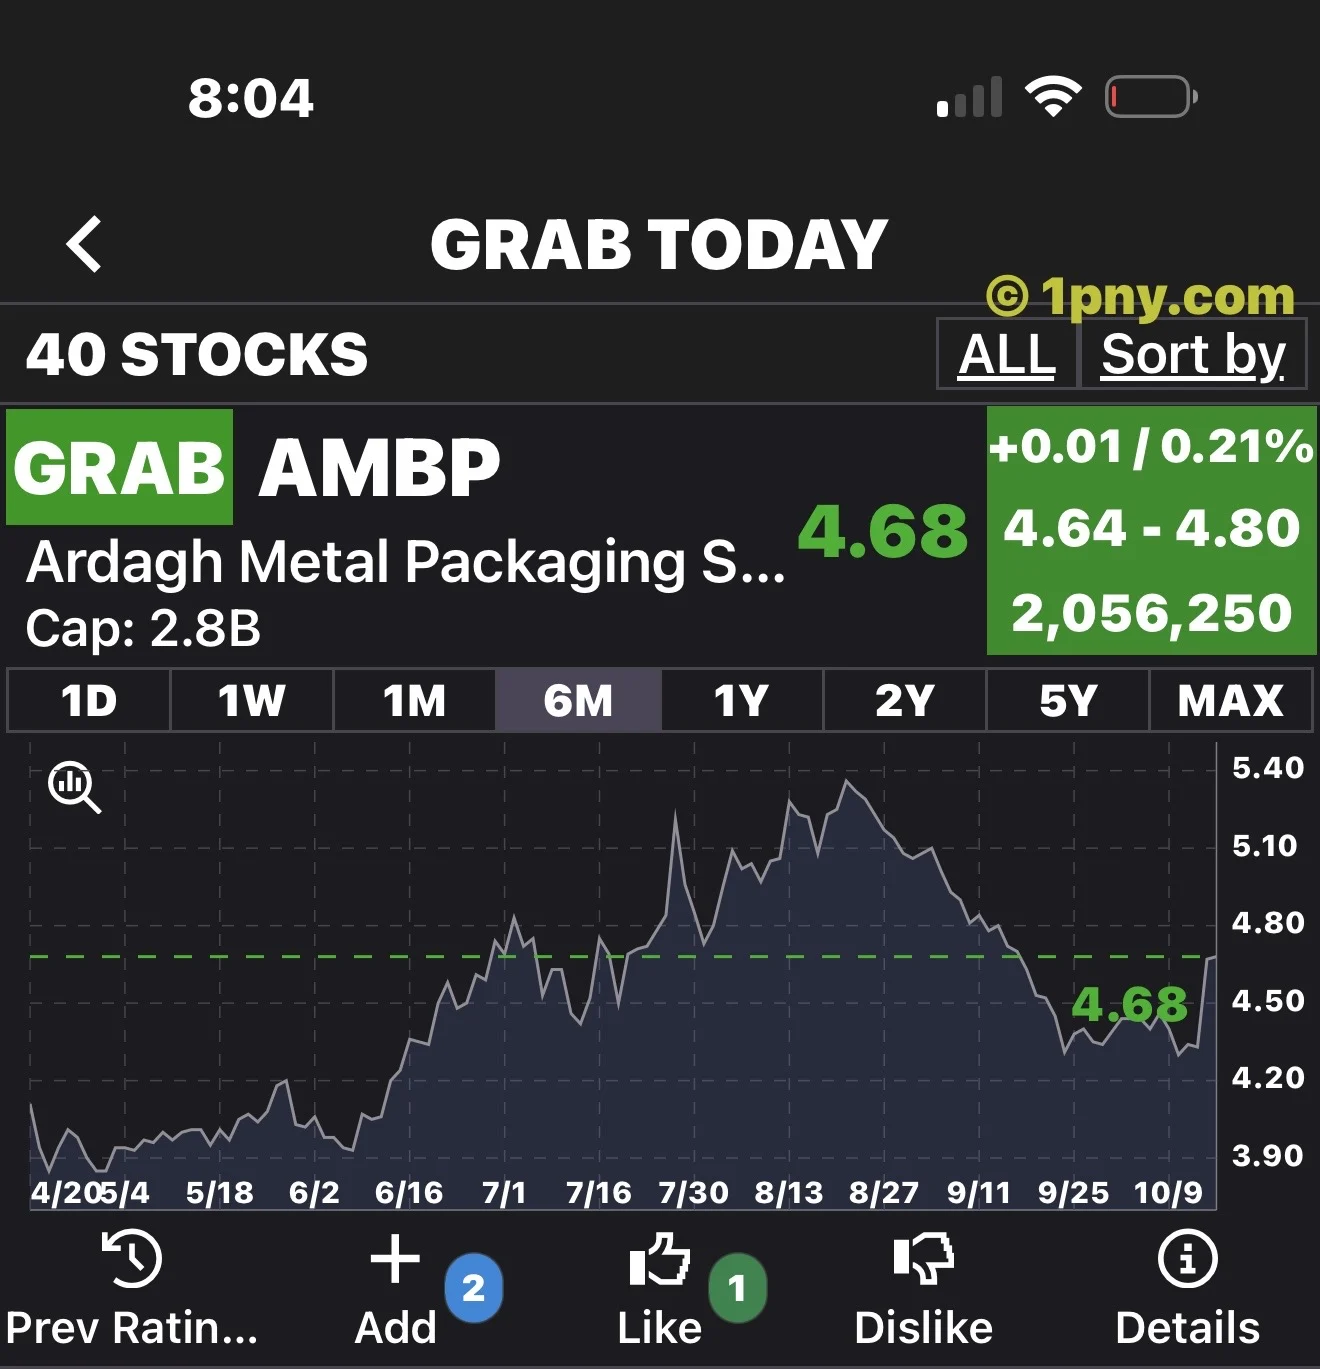
The PennyGems screenshot supplied by the reader displays AMBP at 4.68 with a six-month chart selected. Its visible path includes an earlier rise, a subsequent retreat and a rebound near the right edge. The screen does not establish a complete capture date or identify the quote currency, so that number is a historical illustration rather than an executable market price.
The app’s green GRAB label is the app’s assessment. It is not evidence that Ardagh’s cash flows justify a particular valuation. A chart can help a reader understand the journey that shareholders have experienced; the business analysis must explain what could make the next part of that journey different.
A legal obstacle to preparing a sale was removed
On October 15, Ardagh Holdings said a Luxembourg judge had withdrawn an order that had prevented it from proceeding with a sale of all or part of its AMBP interests. The parent said it could re-engage advisers to prepare for a potential sale. [2]
That creates a genuine development to follow, not a completed transaction. A disposal of a controlling shareholder’s interest need not have the same economics as an offer for every publicly traded share. Readers should look for transaction structure, treatment of minority investors, financing, conditions and the allocation of any proceeds before assigning value to a possible deal.
A sensible investment framework therefore separates a standalone valuation from an optional transaction scenario. If the purchase only works at an assumed takeover price, it is principally a deal speculation.
Debt makes the quality of improvement important
The second-quarter release reported net debt at 5.2 times adjusted EBITDA and anticipated some reversal of favorable first-half timing effects. [1] A business with substantial leverage needs more than an attractive earnings headline: it needs durable cash generation after interest, maintenance spending and other claims on cash.
Our analytical test is whether ordinary shareholders could benefit under conservative operating assumptions without relying on a buyer to rescue the valuation. Better earnings can strengthen that argument, but weak demand or financing pressure can work in the opposite direction.
What would make the bullish case stronger
The next evidence to seek is sustained profitability, cash that remains after necessary investment, and a debt burden that becomes easier to support. Any sale update should be evaluated on its actual terms rather than on the excitement generated by the word sale.
AMBP merits consideration as a leveraged operating-improvement investment with a possible ownership catalyst. A buyer should be able to explain the standalone case, specify what would invalidate it and size the position for a scenario in which the sale never happens. This is a conditional investment thesis, not a promise of gains or a verified current-price recommendation.
About PennyGems, the app behind these screenshots
The stock-chart screenshots in this article were provided from PennyGems, a mobile stock-research app available for iPhone on the App Store and for Android on Google Play. The accompanying image shows its iPhone App Store listing. [4][5]
For readers researching penny stocks trading under $5, PennyGems offers a way to build a shortlist within a broader universe of low-priced shares. Its iPhone listing advertises coverage of over 2,000 stocks under $10. The app updates its buy and sell recommendations daily, with its listings describing updates three times a day. [4][5]
PennyGems helps users spot trending stocks that its system rates as buy candidates, compare opportunities across sectors and industries, and flag penny stocks carrying Sell or Dump ratings for closer scrutiny or avoidance. Charts, watchlists, fundamentals and rating history give readers additional context for investigating those signals. The app’s rankings are research inputs, rather than a guarantee of which stocks or industries will perform best. [4][5]
Get PennyGems for iPhone through the App Store link [4], or for Android through the Google Play link [5] below.