$IPW, $0.44. According to PennyGems App stock analysis a recurring services model could give iPower a different kind of business to develop. The opportunity sounds attractive: support computing equipment for customers rather than judge progress only by equipment ownership. But the economic value depends on a signed relationship, actual deployment and the costs of delivering the service.
The October announcement is a plausible reason for investors to revisit IPW. It does not prove the cause of the exact price movement in the supplied screenshot.
A proposed relationship with an expansion assumption
On October 15, 2026, iPower announced a customer-signed, nonbinding letter of intent for five years of AI-equipment services. An initial 48 units could expand to 396 during 2027. Its $21.90 million annualized fee illustration assumes full deployment at the proposed rate; this is not committed revenue or guidance. [1]
Our interpretation is that an identified service concept is more useful than a broad statement of AI ambition. Even so, customer interest and contracted economics are different stages. A larger potential fleet cannot be treated as equipment already deployed and paying fees.
What the PennyGems screenshot shows
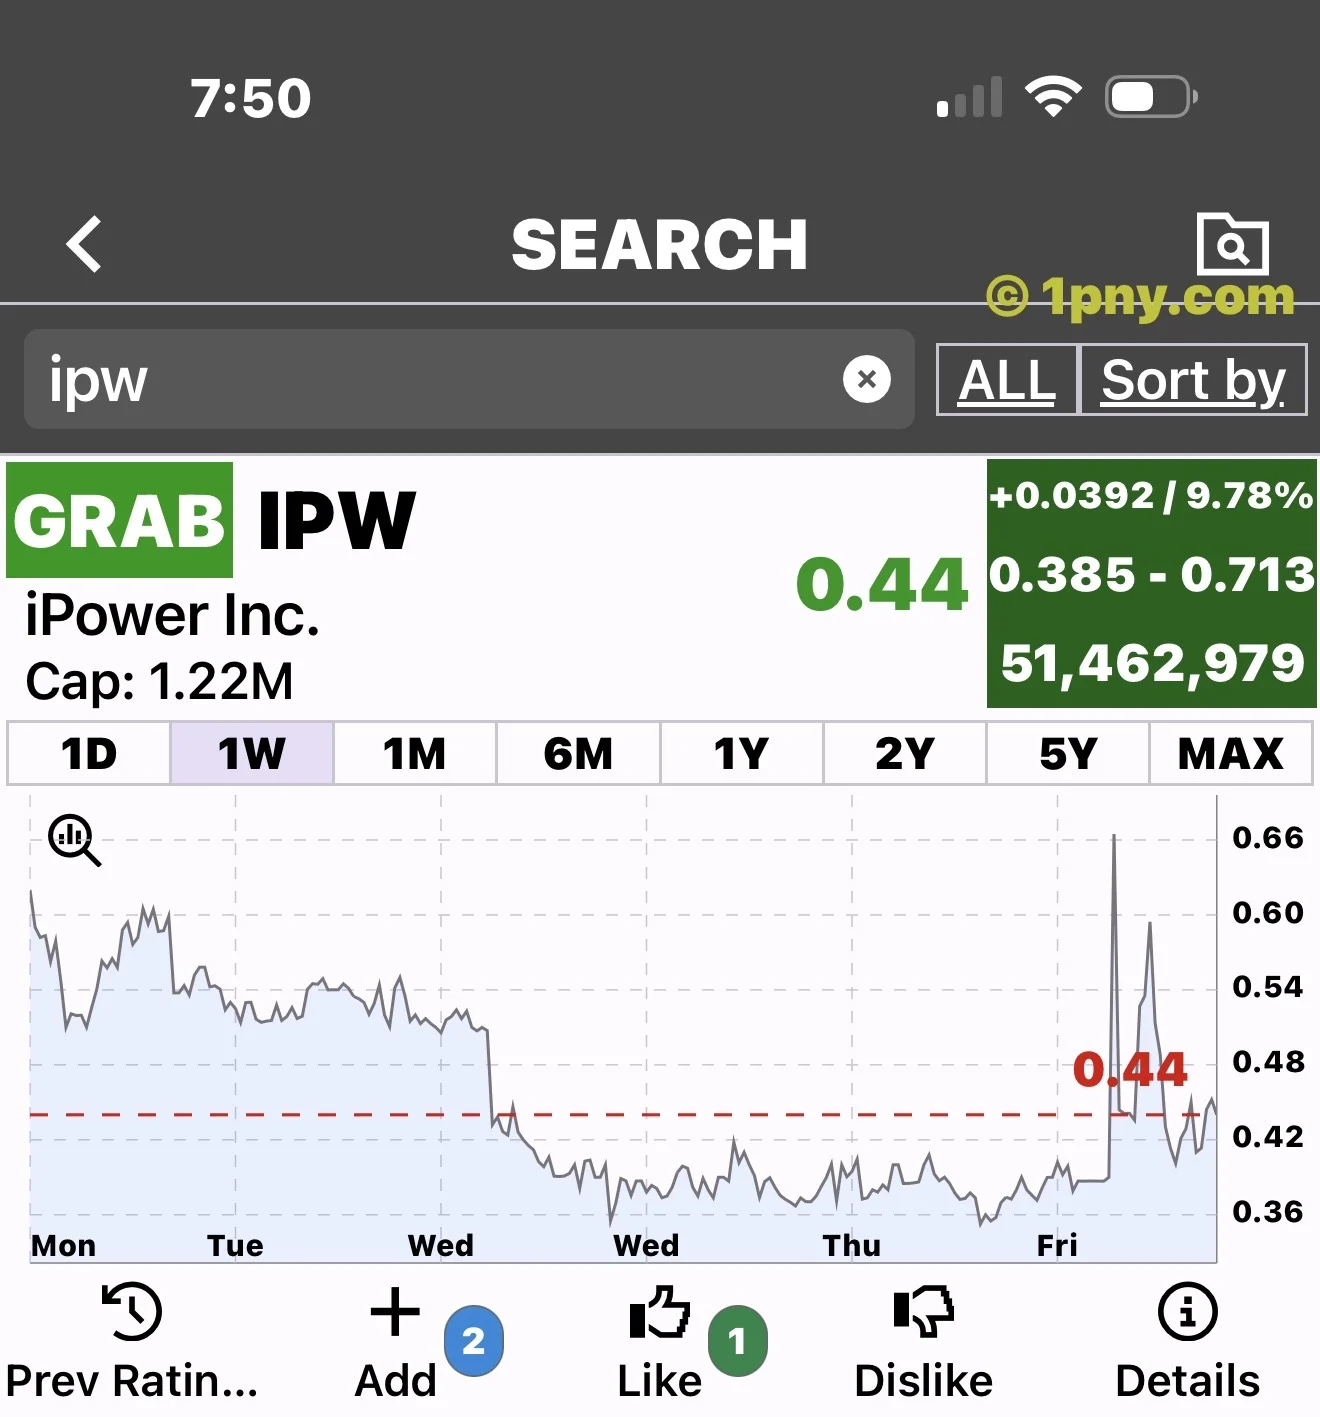
The supplied image displays IPW at 0.44, up 9.78%, with PennyGems’ GRAB rating and a one-week chart selected. The line includes a decline, a sharp spike and a pullback. The complete capture date and quote currency are absent. These are app readings, not independently verified closing returns or our investment rating.
The changing path is a reminder that even a positive daily percentage can coexist with considerable volatility. Neither a brief spike nor a low nominal share price establishes a bargain.
Annualized fees are not the same as annual revenue
A run-rate illustration extends a stated level of activity across a full year. If activity starts later, ramps gradually, changes price or ends early, actual revenue can differ substantially. Profit also requires deducting the expenses and obligations involved in providing the service.
The company’s SEC-filed release says final commercial terms depend on a definitive agreement. [2] We would look for that agreement’s scope, customer obligations, implementation schedule and payment terms before treating the opportunity as backlog.
This is also why multiplying a hypothetical annual figure by five does not establish guaranteed contract value. Each assumption needs support, including whether equipment remains billable and whether the service can be delivered economically.
The next evidence should be commercial
A stronger investment case would show enforceable agreements, deployed units, collected fees and an understandable margin after support and infrastructure costs. Those are separate milestones. Progress on one does not automatically satisfy the others.
We would also evaluate funding needs and any change in the share count alongside operating progress. A new business can grow while delivering disappointing returns to existing shareholders if its capital requirements are too expensive.
IPW offers an interesting AI-services option. The responsible investment question is whether the proposal becomes durable economics per share, not whether a maximum fee illustration is large relative to an app’s market-cap field.
About PennyGems, the app behind the screenshots
The reader supplied these PennyGems chart screenshots. Available for iPhone [4] and Android [5], it helps readers research low-priced stocks, compare sectors and review buy/sell ratings updated daily. Its iPhone listing advertises over 2,000 stocks under $10. These signals can help build a watchlist and flag weaker candidates; they do not guarantee returns.