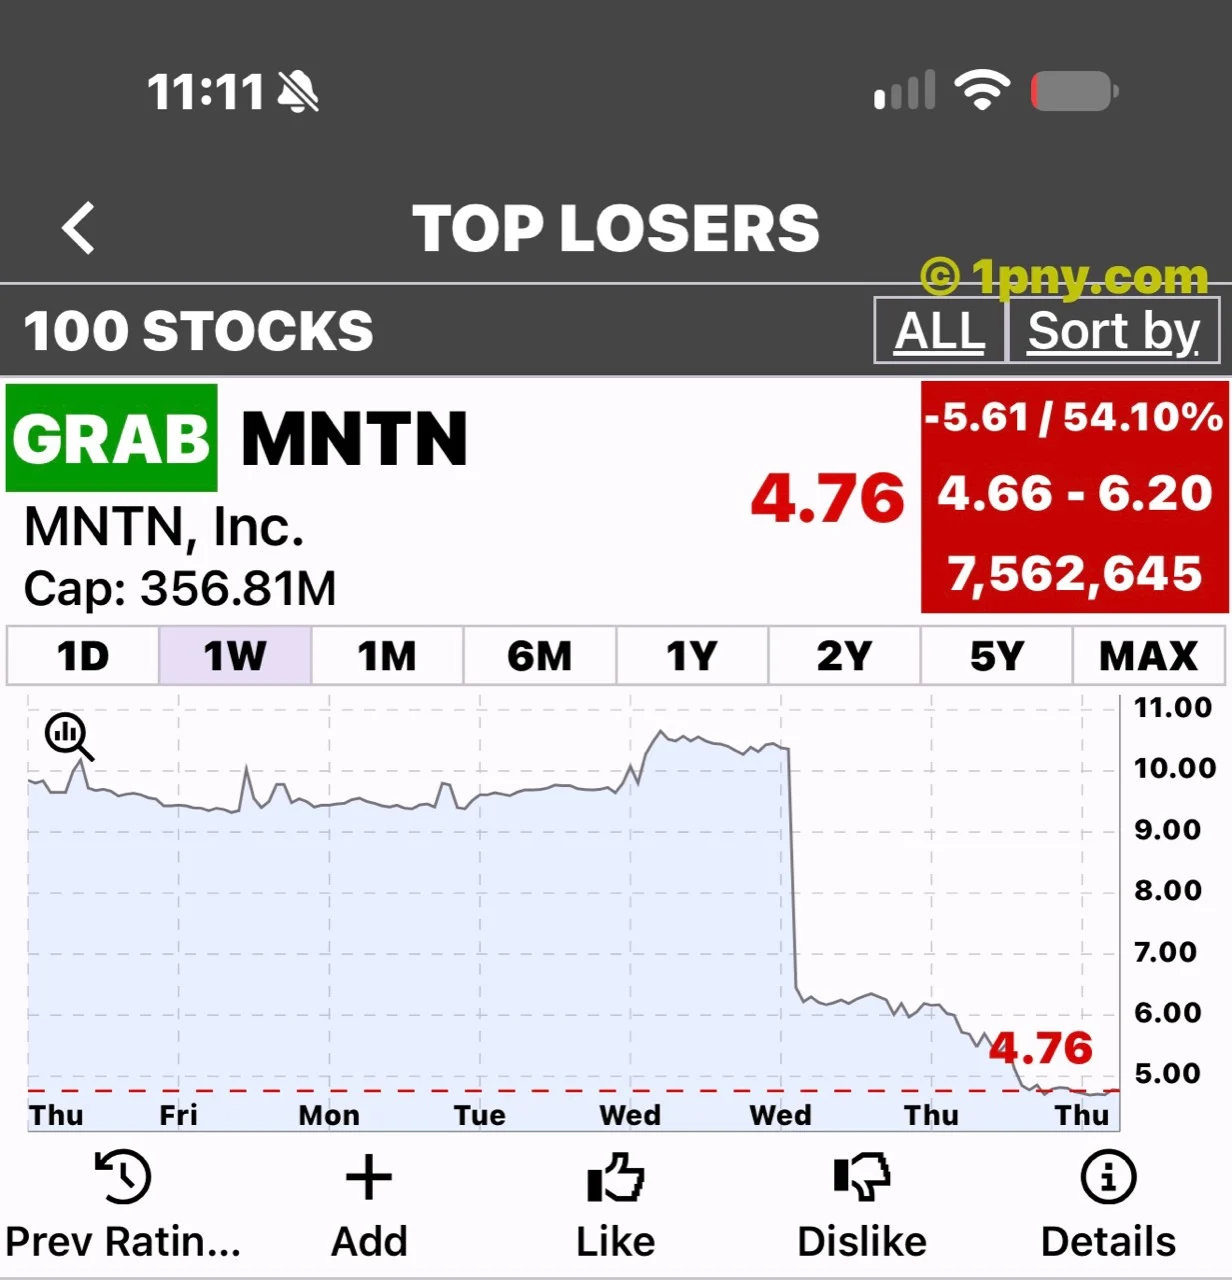
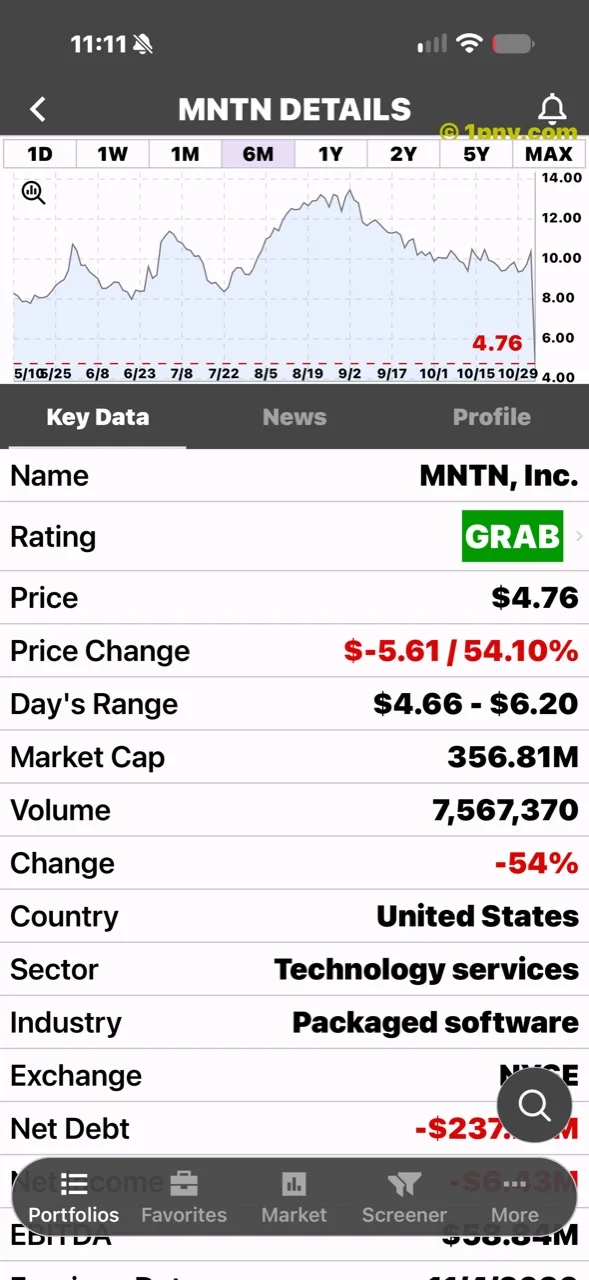
MNTN (NYSE: MNTN) fell sharply after its third-quarter report exposed a gap between a growing business and the growth investors had expected. The reader-supplied PennyGems chart shows $4.76, down 54.10%, with volume of 7,562,645 shares. A separate key-data screen shows slightly higher volume. These 11:11 phone screenshots are market snapshots, not live quotes or closing prices.
The central issue is sales execution. Recent reporting describes a revenue miss, a reduced annual outlook and disruption in the sales organization. Together, those developments offer a concrete explanation for the repricing, although no announcement can establish the motivation behind every trade.
Growth did not meet the expected trajectory
MNTN reported third-quarter revenue of $80.3 million, up 15% year over year, net income of $7.7 million and adjusted EBITDA of $19.9 million. Its updated full-year revenue outlook is $311 million to $314 million. Fourth-quarter guidance calls for revenue of $75 million to $78 million and adjusted EBITDA of $8 million to $10 million. [Company results](https://www.businesswire.com/news/home/20261104123723/en/MNTN-Reports-Third-Quarter-2026-Results).
The distinction between growth and expectations is essential. A company can sell more than it did a year earlier while disappointing shareholders who were pricing in a faster expansion. The valuation can change abruptly when a weaker forecast suggests that the shortfall will extend beyond the quarter just reported.
The fourth-quarter range is particularly useful because it provides a testable near-term benchmark. Its revenue midpoint is below the third-quarter result. Investors must now assess whether that represents a temporary rebuilding period or the beginning of a longer slowdown.
Sales disruption raised questions about execution
Contemporaneous earnings coverage reported that revenue missed the company's prior $86 million to $89 million guidance. It also described the departure of roughly 40% of experienced quota-carrying salespeople following compensation changes. [Earnings-call coverage](https://www.gurufocus.com/news/9173953/mntn-inc-mntn-q3-2026-earnings-call-highlights-sales-force-shakeup-dents-revenue-as-guidance-cut).
This matters because replacing a salesperson is not the same as immediately replacing that person's customer relationships and productivity. Recruiting, training and rebuilding a pipeline can take time. Compensation changes may be reversible, but the commercial effects of staff departures can persist after the original policy has been corrected.
That is an execution concern rather than proof that connected television advertising has stopped growing. The relevant question is whether MNTN can convert available demand into profitable business with its rebuilt sales organization. Future results will provide better evidence than an assumption that either recovery or permanent damage is inevitable.
New leadership has measurable work to do
MNTN appointed Tony Weisman as president and chief executive officer, succeeding Mark Douglas. The company also reported $252.3 million in cash and cash equivalents and no outstanding borrowings at quarter-end.
Those balance-sheet figures are important context: a collapsing share price should not automatically be described as an immediate cash crisis. But liquidity alone cannot restore sales momentum. The company still needs to demonstrate that organizational changes improve execution.
For readers following the turnaround, useful checkpoints include customer additions, spending by existing customers, revenue relative to guidance and the cost of rebuilding the sales team. A recovery becomes more credible when several measures improve together rather than when management merely announces new appointments.
What the screenshot can and cannot establish
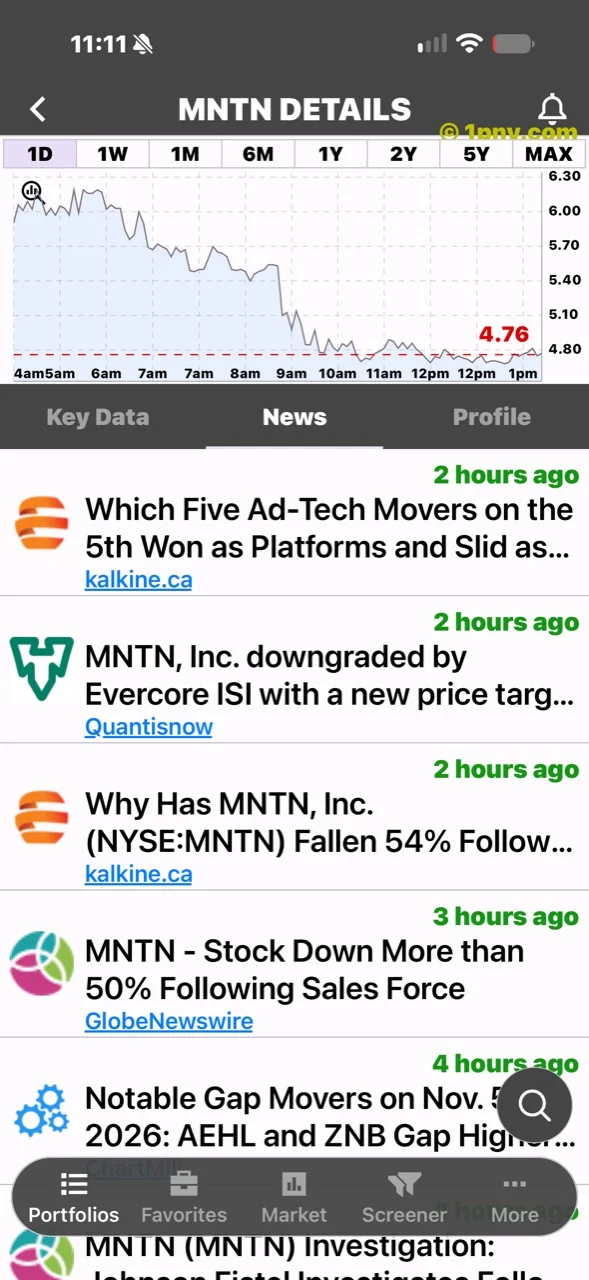
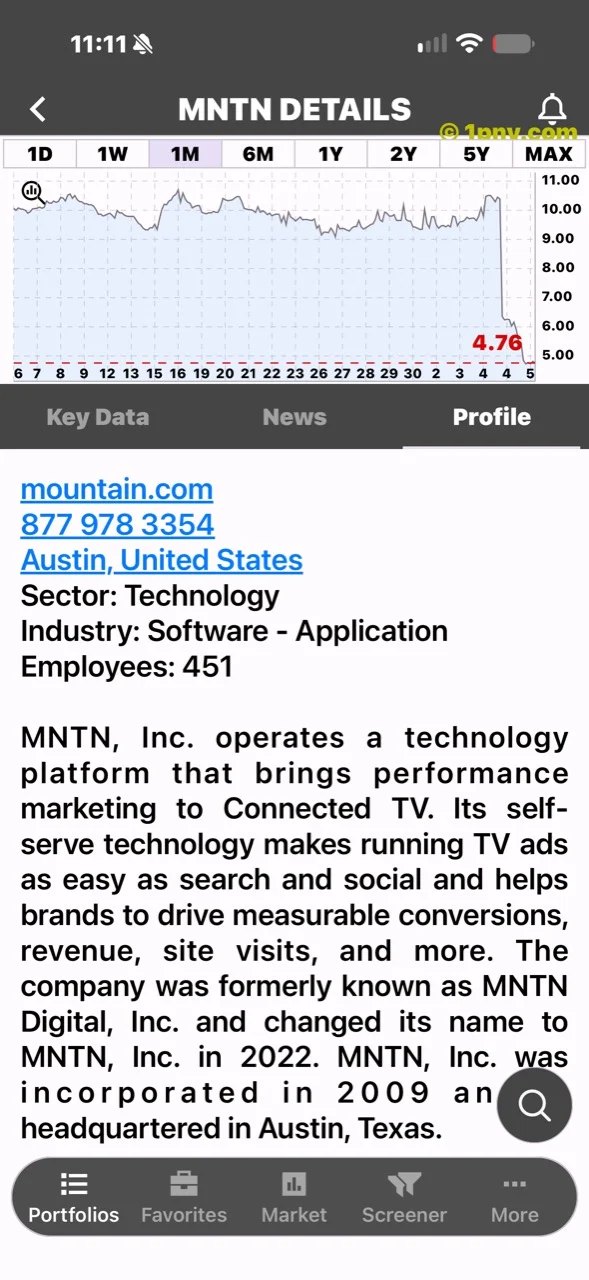
The supplied chart illustrates the severity of the repricing. Its GRAB label is PennyGems' own app signal, not this article's recommendation. News-feed images include truncated headlines and should not be read as independent verification of every claim.
MNTN's story is a reminder that positive year-over-year earnings do not insulate a stock from a lower expected growth path. The next reports will test whether management can repair the sales disruption while preserving profitability. Screenshot credit: PennyGems / 1pny.com.